Both can hold the same economics. Liquidity, credit exposure, and the work of maintaining the position are where they diverge.
Autocallables reached advisors through structured notes for most of their history, which meant evaluating one note at a time: one issuer, one set of terms, one maturity date. The economics inside those notes are the same economics a fund holds today.
A contract held in a fund seeks income the way a note does, from option-like economics tied to a reference exposure, and it carries similar conditions on income and principal. What changes is everything around those economics: how the exposure is priced, how it is bought and sold, whose credit sits behind it, and who does the work of maintaining it.
What changes in the ETF wrapper
Liquidity
A note is generally designed to be held to maturity. A secondary market may exist, but pricing in it can be thin and hard to verify, which makes an early exit a negotiation rather than a trade.
A fund prices daily and trades on an exchange during market hours. That does not fully remove liquidity risks as spreads on any ETF can widen in stressed markets, but the exit is an order with price discovery rather than a call to a desk.
Transparency
Comparing two notes means reconciling terms that vary by issuer, exposure, barrier level, tenor, and call schedule, with embedded cost that is often not itemized anywhere you can see it.
A fund publishes its holdings, its fee, and its terms in a standardized format. You can see which contracts are held, when they are observed, and where their levels sit, and you can compare that against another fund on the same basis.
Credit and counterparty risk
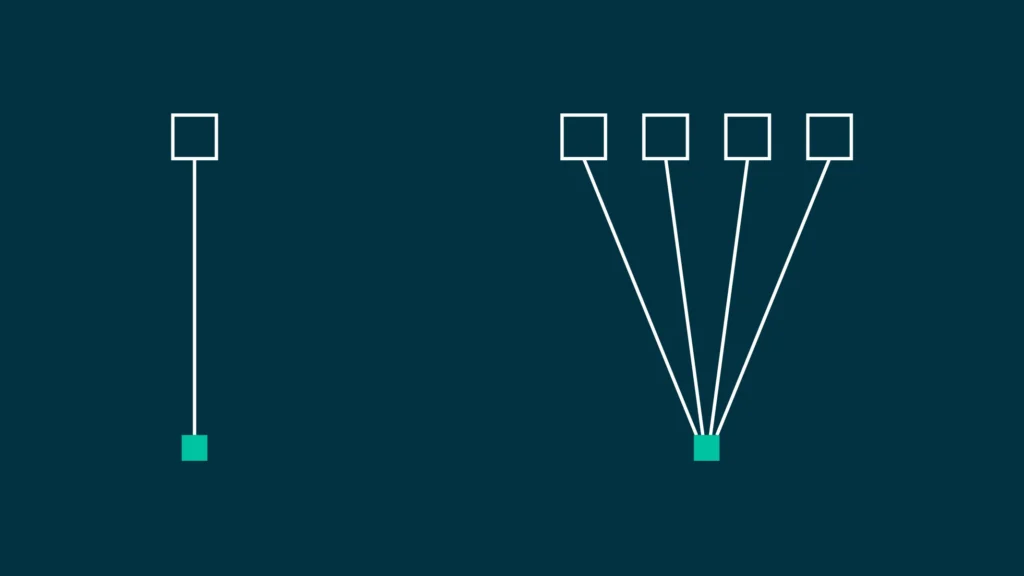
A note is generally an unsecured debt obligation of the issuing bank, which means your client holds two risks rather than one: the behavior of the exposure, and the creditworthiness of that single bank for the life of the contract.
A fund may access the same economics through over-the-counter swaps governed by ISDA agreements, transacting with multiple derivative counterparties, with exposures marked-to-market and collateralized under those agreements. Counterparty risk does not disappear. What changes is that it is spread across counterparties, collateralized, and repriced daily rather than concentrated in one balance sheet until maturity.
Minimums and access
Notes have moved largely through private bank, wirehouse, and institutional channels, with minimums, client documentation, and coordinated execution attached to each one.
A fund is a ticker. You can size a position to the account rather than to the minimum, and you can hold the same exposure across every account that needs it without sourcing and documenting a separate note for each client.
A fund also holds many contracts at once, with different start dates, observation dates, and maturities, rather than concentrating the strategy in one set of terms.
What the wrapper does not change
The economics are untouched. A contract held in a fund still seeks income by accepting defined equity-linked risk under stated conditions, and outcomes still depend on where the exposure sits relative to its levels on the dates it is observed. Nothing in the wrapper improves a coupon or softens a maturity barrier for the individual contracts.
What the wrapper changes is who carries the implementation. Pricing, execution, documentation, collateral management, and the work of maintaining and diversifying exposure over time moves from your desk into the fund. That is worth evaluating on its own terms, and it is a separate question from whether the strategy belongs in your client’s portfolio.
Disclosures:
All investments involve risk, and the past performance of a security or financial product does not guarantee future results or returns. There is always the potential of losing money when you invest in securities or investment strategies. Investors should consider their investment objectives and risks carefully before investing. Options have specific investor risks. The opinions and forecasts expressed may not actually come to pass and should not be construed as a recommendation of any specific security or strategy. All content has been provided for informational or educational purposes only. Target Outcome Investments® and Target Buffer® Strategies® are registered trademarks of Vest Financial™. Investment advisory services are provided by Vest Financial LLC, an SEC-registered investment adviser. Financial professionals are responsible for evaluating investment risks independently and exercising independent judgment to determine whether investments are appropriate for their clients.